
The case for Europe aggressively building its own tech infrastructure (what EuroStack stands for) is not primarily security or resilience in the face of the “killer switch” threat. Yes, those are part of the narrative but the tale of “the judge in the Hague” allegedly turned off by Microsoft at the request of the US Administration is somewhat stale by now. If we power ourselves up, resilience and security will be improved as a natural implication. Having alternatives self-evidently increases our bargaining position against attempts at coercion and weaponisation of US digital services against Europe. This goes without saying: if your own assets and capabilities are shrinking, in the expression favoured by President Trump “you have no cards”.
But this is not the primary motivation for why our own tech infrastructure (from chips to cloud to software to connectivity to AI) needs to be aggressively built up. Neither is an adversarial posture towards US digital incumbents (other than to the extent they behave exploitatively towards European businesses and consumers). Nor is discourse around the“threat to democracy” associated with the presence and influence of “tech oligarchs” in Europe. Europe has a strong set of values and a democratic tradition we are all proud of. But the main motivation for the EuroStack Industry Initiative is another one.
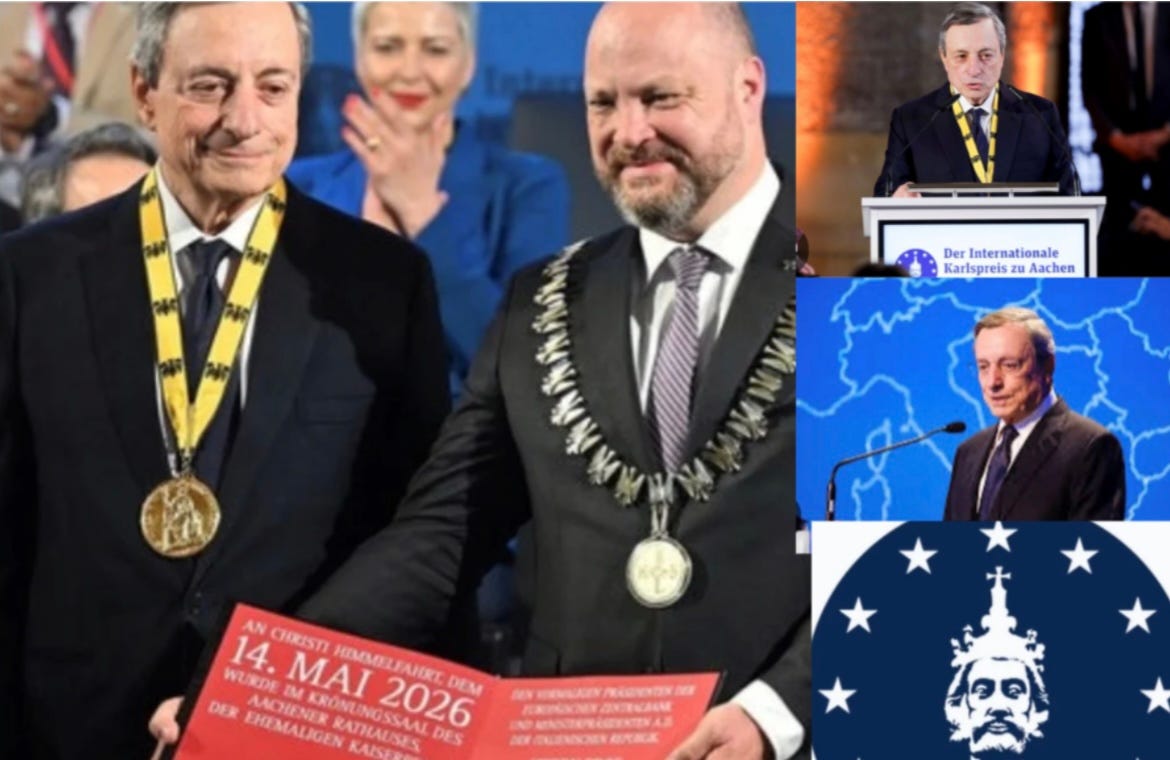
And it has been reiterated with characteristic clarity in Mario Draghi’s exceptional acceptance speech for the Charlemagne Prize last Friday in Aachen (see here). In the speech, a must-read, Draghi doubles down on his now famous “productivity growth chart”: the stark picture in his 2024 report showing European and US hourly productivity growth increasingly diverging after 2000, most strongly after 2019, and how this means Europe’s performance will continue to deteriorate in relative terms if we don’t act fast and radically. His sombre assessment in Aachen was that things have not improved since, and in fact he now estimates the investment needed for Europe to make a dent in the problem to be nothing short of “immense” – up to 1.2 trillion a year from 800bn in 2024. Europe cannot generate investment on this scale without powering up major growth.
As it happens there has been a lively debate in the last few weeks on the “productivity growth” diagnosis – with US economist Paul Krugman positing a more benign interpretation that “things aren’t after all so bad for Europe”(“France is not Mississippi” see here and here); and Luis Garicano reacting strongly, with postings pushing back on Krugman’s assessment and arguing this kind of forgiving narrative from overseas’ casual visitors to Europe (the “walking around test”) is emphatically unhelpful to the reform project in Europe (economists really got stuck in! see Bergeaud, Voth, others). A side debate has also flourished between Garicano, Wolff and others, focusing on intra-European differences (Garicano finds the Eastern flank states like Poland are in fact killing it, while the real losers being left behind are France, Italy, Spain, Germany). Many more chipped in - too many to mention - with repostes and observations on data used and measurement. BUT the fundamental message remains that (pro bona pace of Krugman) Europe is confronting an existential economic crisis of growth which just not soluble with current means.
Draghi’s Aachen speech doubles down on his 2024 diagnosis, connecting dots in way only he can. Given the investment need, “growth is the condition for everything Europe now says it must do”. This is an existential issue and the hurdles are huge:
First, the economic model that enabled Europe to generate prosperity for the past few decades is no longer viable. Draghi calls out the “contradiction” at the heart of the model: Europe “built the most open major economy on earth” with external demand (exports) relied on to absorb European products. This external “search for growth” was necessary as domestic demand was suppressed by our known failures (no real Single Market, no capital market, no energy strategy), and swathes of regulation. The safety valve of external demand is now over as China is regurgitating its massive surplus on Europe and tariffs foreclose US markets further (European exports to the US have fallen 17% since Liberation Day). Other trade deals will not rescue us.
The “second vulnerability” is “our growing strategic dependencies” where Europe again is to blame. We took a “defensive path” with low risk taking, “don’t rock the boat” as the rule, and regulation as default. Now “we are truly alone together” and “responding with a system that was not designed for challenges of this magnitude”.
The “third vulnerability”, perhaps the most serious, is “Europe’s deteriorating position” in tech, and especially in the “technologies that will define the next decade”. Here Draghi directly resurrects his 2024 productivity growth analysis: he points again to the “growing divergence in productive capacity, reflecting not only America’s larger technology sector, but the deeper digitalisation of American firms and workflows”. What’s more now it is clear AI will be essential and transformative, yet “Europe is falling behind” even though “this is not a gap we can afford to let widen”.
This is where EuroStack really sets its stall. “Digital sovereignty” was a strong theme in Aachen last year and I was on a panel making these points: we need productivity growth, and building our infrastructure matters. Again, think of the reasons for the divergence in productivity growth between Europe and the US: when Adam Tooze dug into it in the wake of Draghi’s 2024 report, he argued the data shows Europe is falling behind because the US threw in more investment per worker in tech (“workers equipped with more capital tend to be more productive”). And, as digital is an all-purpose technology that pervades all sectors of the economy, this supported productivity growth overall.
Europe is at present a digital colony. Our digital infrastructure is almost entirely owned by actors whose ultimate control (don’t mean location, don’t get bamboozledby “sovereignty washers”) resides outside Europe. The reason this matters is value capture. If you do not own and control the means of production, if you are just at the receiving end of multiple layers of ownership and control, if you are just buying access to them and building your thing on top, you are not capturing the rents in the value chain. And this matters not “just” because that way you have no control on the direction of innovation, and because you can be held to ransom. But above all because someone else captures most of the value, syphons off profits, and investment decisions are made elsewhere. If we are utterly dependent on external actors for the creation of that value, then we are exposed to coercion, yes, but above all we are not appropriating enough of the value of the services sold to and paid for by Europeans. Much of that value is exported back to the parent outside Europe and goes to fund non-European innovation and investment. It does not translate into profit generation by European agents and re-investment by Europeans in Europe to strengthen our economy. That’s the point.
And this will be true in spades with AI, which really poses a dilemma. We can jump on the horse and go hell for leather adopting AI every which way – BUT at present we can mostly do it using hyperscaler stacks (platforms, models, compute, data processing, cybersecurity all conveniently integrated into one, e.g. for agentic AI); OR we don’t and the consequences are too dire to contemplate. So we only really have option one (and I personally do think we need to truly throw everything at it - ethical concerns and job armageddon are not a show-stopper for me). BUT it should also be clear we arfaeat risk of entrenching further the power of the Usual Suspects (see my podcast with the ever-splendid Luis Garicano on this). AI is cloud, and if we are a digital colony in cloud we are not suddenly entering a magical kingdom where we are “sovereign” in AI – industrial AI will give us a chance, maybe (unique European skills and industrial data), but we are not magically going to become “sovereign”. There may be enough competition today between giants that the rent extraction phase is postponed. But at some point, the squeeze may well come – like in digital, we will be not only dependent but paying large rents to others.
Draghi’s Aachen speech is of course a restatement - ever more urgent – of the problem. He is not in charge (for now) of getting the wagon on the tracks. Our politicians and private enterprise are, though paralysis still prevails, and “hope as a strategy”. But he is clear Europe’s yoke are our dependencies, majorly in tech – and this is exactly the EuroStack pitch: we must build more European assets and capabilities to support growth.
We are also saying similar things to Draghin on multiple related issues:
- Significantly, he approves of “Made in Europe”, “as a way of using European demand more deliberately(…). Without demand of its own, Europe cannot sustain a credible posture abroad”. A-men. This is why we have supported demand-side tools like “Buy European” in digital procurement – as one of the ways in which European suppliers can be supported: by directing a modest portion of taxpayer money towards European vendors. Not 100% of it, not even half of it. But we need to account for a larger share of supply in our own market. NONE of this means protectionism or decoupling or autarchy. It increases competition, not reduces it.
- “Europe cannot reshore every critical technology by itself. The cost would be prohibitive”. Indeed. Again we are not “decoupling” (silly word) - we will be happy to work with non-European suppliers for a long time to come (including from the US, even though this partner “has become more adversarial and unpredictable” and our search for negotiation and compromise “has mostly not worked”).
- “Europe needs the ability to respond more assertively to put the partnership on more equal terms”. Again, yes. We are just absorbing shocks all the time – including our rolling over de facto on tech regulation. Defence will be key to this and tech is integral to defence as we have tremendous potential for the era of asymmetric warfare.
This is important for everyone to understand, as people seem to think it’s an unusual point when I make it: the case for EuroStack is not security or resilience alone. It is not “our values and our democracy” alone. Again, it is primarily growth. And unless we move on that chessboard, with suppliers getting better at products customers want to buy, the demand side proactively evaluating European alternatives, and funders being willing to dip their toes into European tech, we are stuck. No amount of uplifting talk on “our values” will get us anywhere. We are beginning to see movement though. Europeans are beginning to realize “we are a super power, and we must act like one” – even if our politicians remain hapless and our captains of industry are no real leaders, still too scared of risk and costs. Still, good to see we are entirely in the “Draghi groove”, and nothing matters more than this in Europe today.